

In the world of running, sprints and marathons demand opposing techniques, preparation, and endurance. A sprint relies on maximum speed over a short duration, while a marathon rests on long-term consistency and stamina.
The same principle applies to managing personal finances. There is no single strategy that fits every situation. Both financial sprints and marathons offer unique advantages and challenges, depending on your financial goals and current momentum.
Understanding the Difference Between Financial Sprints and Marathons
| Feature | Financial Sprint | Financial Marathon |
| Primary Focus | Reaching a specific target in a short time | Building habits and long-term stability |
| Savings Style | Strict and aggressive (extreme saving) | Balanced and measured (sustainable pace) |
| Main Risk | Financial burnout (frugal burnout) | Risk of losing momentum if too slow |
| When to Use? | Paying off debt, saving a down payment, emergency situations | Retirement savings, education funds, daily cash flow |
When Should You Use a Sprint Strategy?
A sprint approach requires you to significantly cut non-essential expenses and allocate as much money as possible toward a single urgent goal.
Pros:
-
Fast Results: Delivers a significant impact in a short period, which is especially useful for clearing urgent financial burdens.
-
High Focus: Makes energy allocation easier by channeling all effort toward a single finish line.
Right Momentum:
-
Paying off high-interest consumer debt.
-
Building up the remainder of an emergency fund that hasn't reached its safe minimum threshold.
-
Chasing the remaining target for business capital or a down payment with an approaching deadline.
When Should You Use a Marathon Strategy?
A marathon approach focuses on a balanced daily allocation rhythm, such as applying the 50/30/20 Method, allowing you to enjoy your current lifestyle without sacrificing future needs.
Pros:
-
Sustainable: Minimizes the risk of stress or mental fatigue because lifestyle needs and self-care are still accommodated.
-
Habit-Forming: Builds financial discipline that lasts for years.
Right Momentum:
-
Managing daily and monthly operational finances.
-
Retirement planning or long-term investments.
-
Preparing children's education funds with deadlines several years away.
Combining Marathons and Sprints in Your Financial Ecosystem
Wise financial managers rarely choose just one; instead, they alternate between both depending on their life stage.
To keep both strategies running smoothly without disrupting your primary cash flow, keep your budget categories neatly separated:
1. Use Separate Pockets for Each Strategy
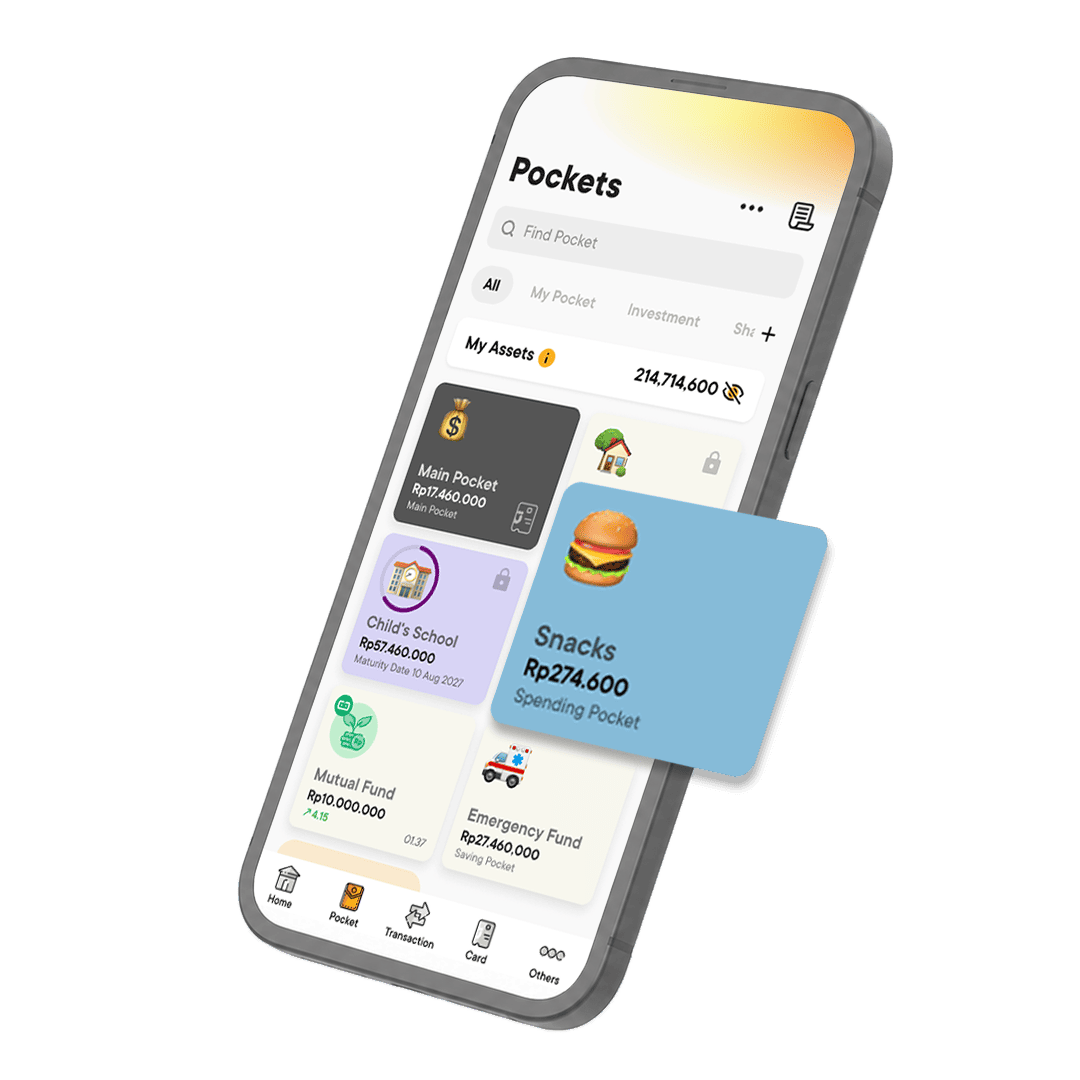
Create dedicated categories using the Jago Pockets tailored to your focus. Use a separate Saving Pocket for sprint targets (so funds build up fast without disruption), and regular Spending/Saving Pockets for monthly marathon goals.
2. Automate Budget Allocation
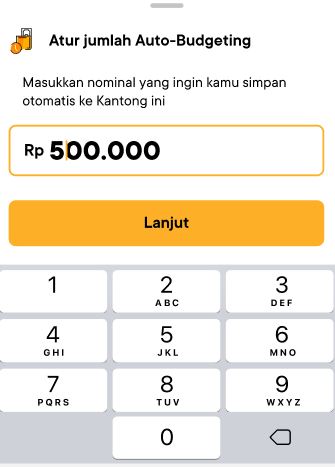
Whether running fast or keeping a steady pace, leverage the Auto-Budgeting feature in the Jago app to automatically transfer funds on payday according to your set target ratios.
Knowing when to step on the gas (sprint) and when to maintain a steady pace (marathon) is the ultimate key to creating a healthy, flexible, and resilient financial portfolio in any condition.