

Preparing higher education funds for a sibling is often a shared responsibility in many families. Whether as an earning older sibling or in collaboration with parents, pooling money for university tuition is a remarkable form of care.
However, managing finances together across multiple people is no easy task. Without accurate numerical planning and transparency, these good intentions can easily trigger misunderstandings down the road.
To ensure the process of saving for your sibling's university fund runs smoothly and consistently, here are practical steps your family can apply:
1. Calculate the Target Fund by Accounting for Education Inflation
The biggest mistake when preparing school or university funds is assuming the cost will remain the same as current rates. In Indonesia, you and your family need to account for annual education inflation.
Savings Target Simulation
If the admission fee and estimated tuition for your sibling currently total Rp50,000,000, and they will enter university in 3 years:
-
Projected cost (assuming 10% inflation/year) = Rp66,500,000.
-
Family monthly savings target (divided over 36 months) = Rp1,850,000 per month (combined total for all family members).
2. Agree on a Commitment and Fair Contribution Ratio
Saving together does not mean splitting the amount equally. The financial capacity of each family member varies.
-
Hold an open discussion regarding everyone's capabilities (e.g., parents support 40%, first sibling 40%, second sibling 20%).
-
Agree on a monthly savings execution date, ideally processed 1–2 days right after each person's payday.
3. Prepare a Plan B: How to Handle the Risk of Family Members Falling Behind Mid-Way
Life dynamics like lay-offs, business slowdowns, or sudden medical needs might force a family member to temporarily stop contributing. To prevent the college fund from stalling or sparking internal conflict, set up risk mitigations early on:
-
Build a Buffer Fund (10% Extra): When setting monthly targets, add a reserve of around 10% of the total monthly contribution as a cushion if a member misses a payment.
-
Periodic Ratio Adjustment Option: Agree on an evaluation every 6 months. If a member experiences a drop in income, redistribute contribution amounts honestly without assigning stigma.
-
Timeline Diversification Option: If total capacity is permanently reduced, consider adjusting your investment strategy to instruments offering higher yields to cover the gap, rather than forcing an amount that disrupts the personal cash flow of other family members.
4. Use a Dedicated Account with Transparent Access
Entrusting shared savings to a single family member's personal account carries high risk. Beyond the danger of getting mixed with daily spending money, the lack of transparency can trigger suspicion.
The best solution is using a financial management app that supports safe collective fund management:
-
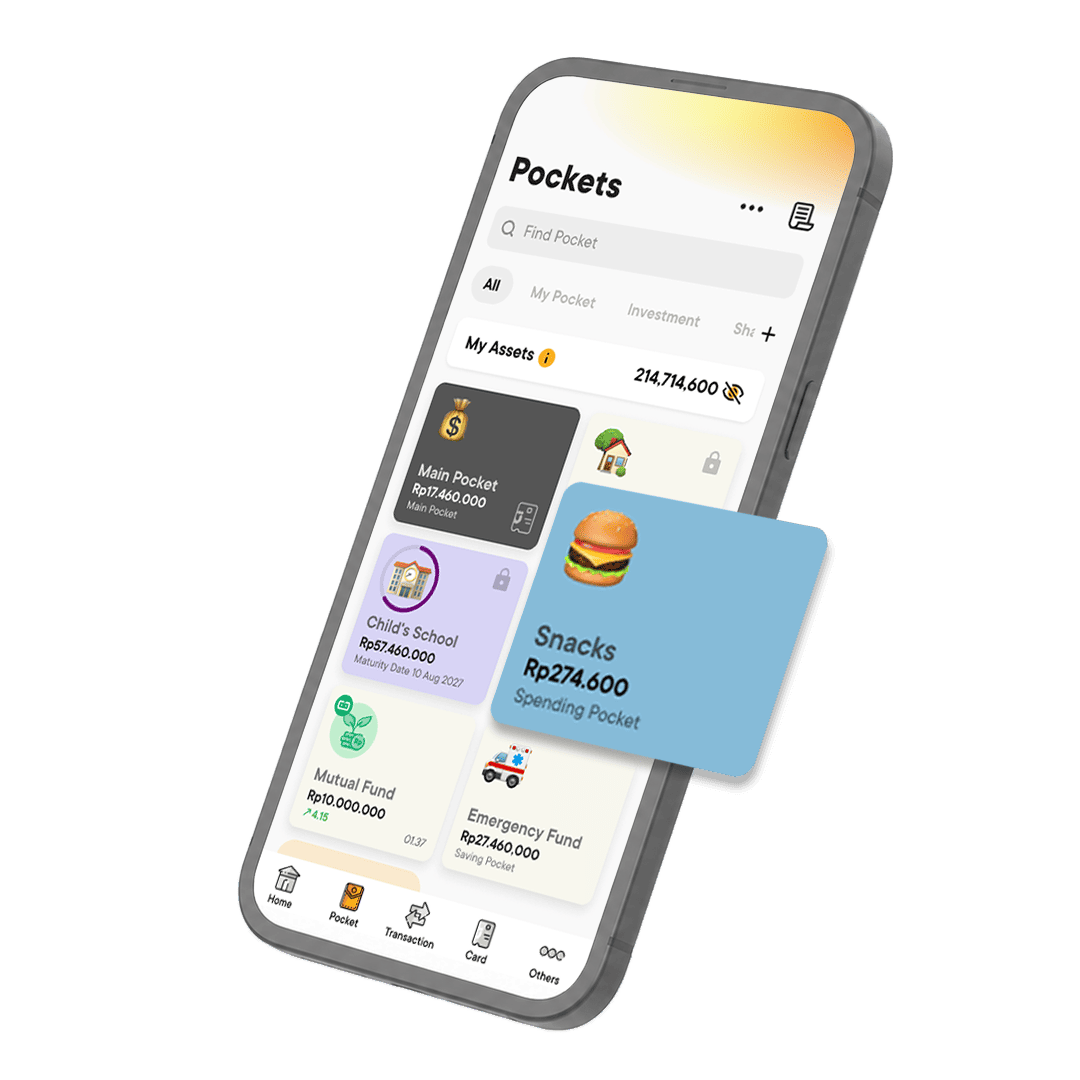
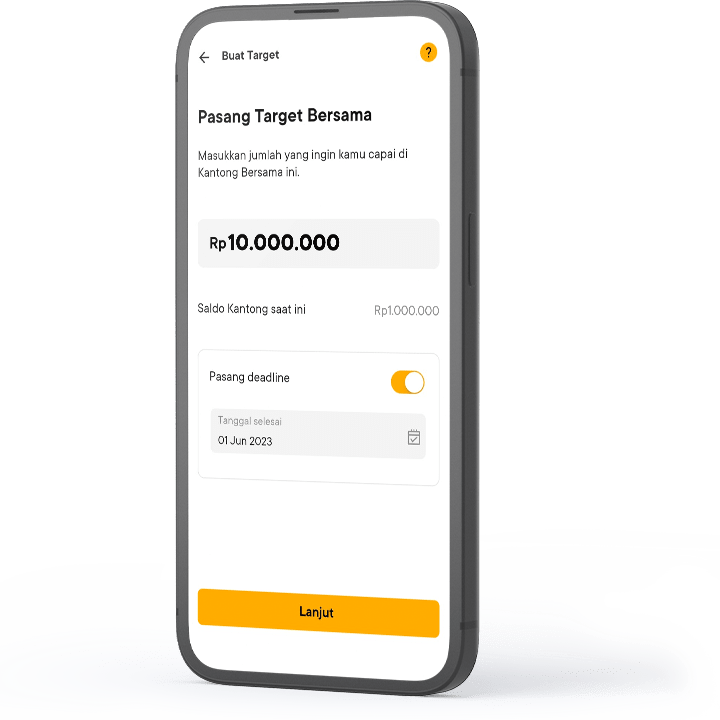
Utilize Jago Shared Pockets: Create a dedicated Pocket for your sibling's college fund, then invite your parents and siblings into the Pocket.
-
Real-Time Transparency: Every joining member can view the accumulated balance and transaction history directly from their respective apps.
-
Clear Roles & Access: The Pocket owner can adjust member access rights (whether they can only deposit or also withdraw funds), keeping your sibling's college fund secure until registration day arrives.
5. Automate Monthly Deposits So They Aren't Missed
Maintaining saving consistency over many months requires a structured habit. Utilizing the Auto-Budgeting feature helps transfer fund allocations automatically from each family member's main account according to the agreed-upon date.
With realistic cost planning, a sound compromise strategy, and a transparent savings container, the dream of putting your sibling through higher education can be realized peacefully without overburdening a single party.