

Natural disasters such as floods, earthquakes, or extreme weather can strike without warning. Beyond threatening safety, disaster crises often carry a significant financial impact, ranging from independent evacuation costs and home repairs to daily cash flow disruptions caused by halted work activities.
Having a crisis-specific financial plan is not wishing for bad things to happen, but rather a wise step to ensure you and your family have financial resilience when an emergency strikes.
3 Pillars of Financial Risk Mitigation and Practical Ways to Manage Them Using the Jago App
To keep your financial portfolio resilient during a sudden crisis, here are three main pillars of financial planning that you can practically apply through the Jago app ecosystem:
1. Build a Disaster Emergency Fund with High Liquidity
In post-disaster crisis conditions, the need for readily accessible cash is extremely high to cover urgent logistics, medical supplies, or temporary shelter costs.
-
Ideal Target: A minimum safety cushion of 3 to 6 times monthly expenses (or up to 12 times monthly expenses for those with dependents).
-
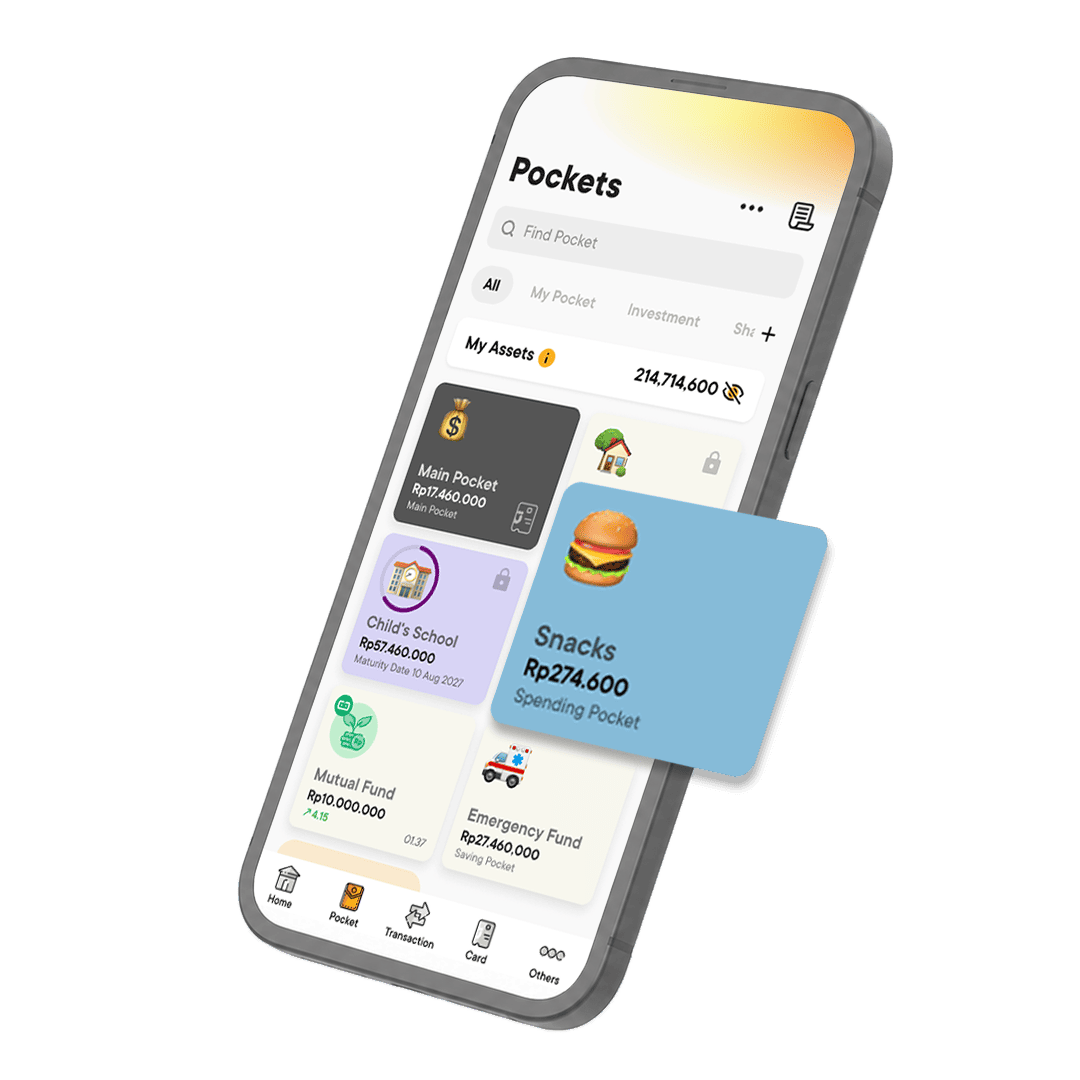
Jago Solution: Create a dedicated Jago Saving Pocket named "Disaster Emergency Fund". If the accumulated emergency fund grows large enough, you can transfer it to a Jago Term Deposit. Jago Term Deposits offer competitive yields and can be withdrawn instantly at any time through the app without penalty fees, making them highly flexible when sudden crisis funds are needed.
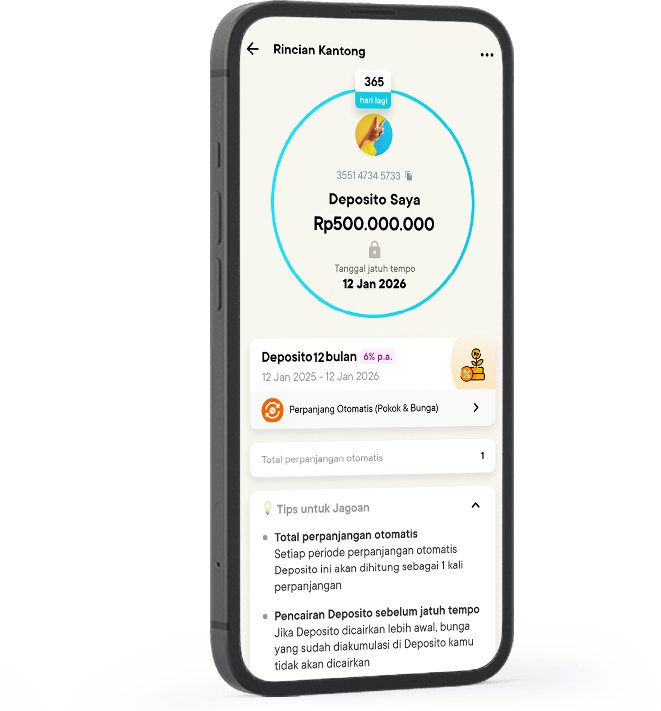
Disaster Crisis Budget Simulation
If your family's routine monthly expenses are Rp6,000,000, the minimum emergency fund target is Rp18,000,000. Allocating Rp1,500,000 per month through a Jago Saving Pocket will secure this minimum safety threshold within 12 months.
2. Secure Primary Cash Flow with Digital Budget Separation
When a disaster strikes, unexpected expenses will surge. Keeping all your money in a single daily account will impact your monthly operational cash flow and risk disrupting other routine bill payments.
-
Mitigation Strategy: Establish clear boundaries between monthly operational money, emergency funds, and daily needs to keep finances under control.
-
Jago Solution: Use separate Jago Spending Pockets for daily operations and mandatory bills. When a crisis occurs, simply execute a budget freeze on your lifestyle Pockets and redirect the remaining budget from your daily Spending Pocket straight into your Emergency Fund Pocket without disturbing your primary bill allocations.
3. Transfer Financial Risks by Saving Insurance Premiums in a Separate Pocket
Emergency funds serve to cover short-term needs. To mitigate large-scale financial losses, such as severe property damage or advanced medical treatment costs, you need to transfer those risks to protection instruments like health or property insurance.
-
Mitigation Strategy: Set aside premium payment funds consistently so your insurance policy remains active and does not lapse when a crisis hits.
-
Jago Solution: Create a separate Jago Saving Pocket specifically named "Insurance Premium Fund". You can set aside a portion of money monthly into this Pocket and activate Auto-Budgeting along with automatic payments, ensuring annual or monthly premium funds are always ready on time without eating into your daily budget.
By applying these three pillars of financial risk mitigation in a structured way through the Jago app, you can protect your family's financial stability while staying prepared to face future uncertainties.